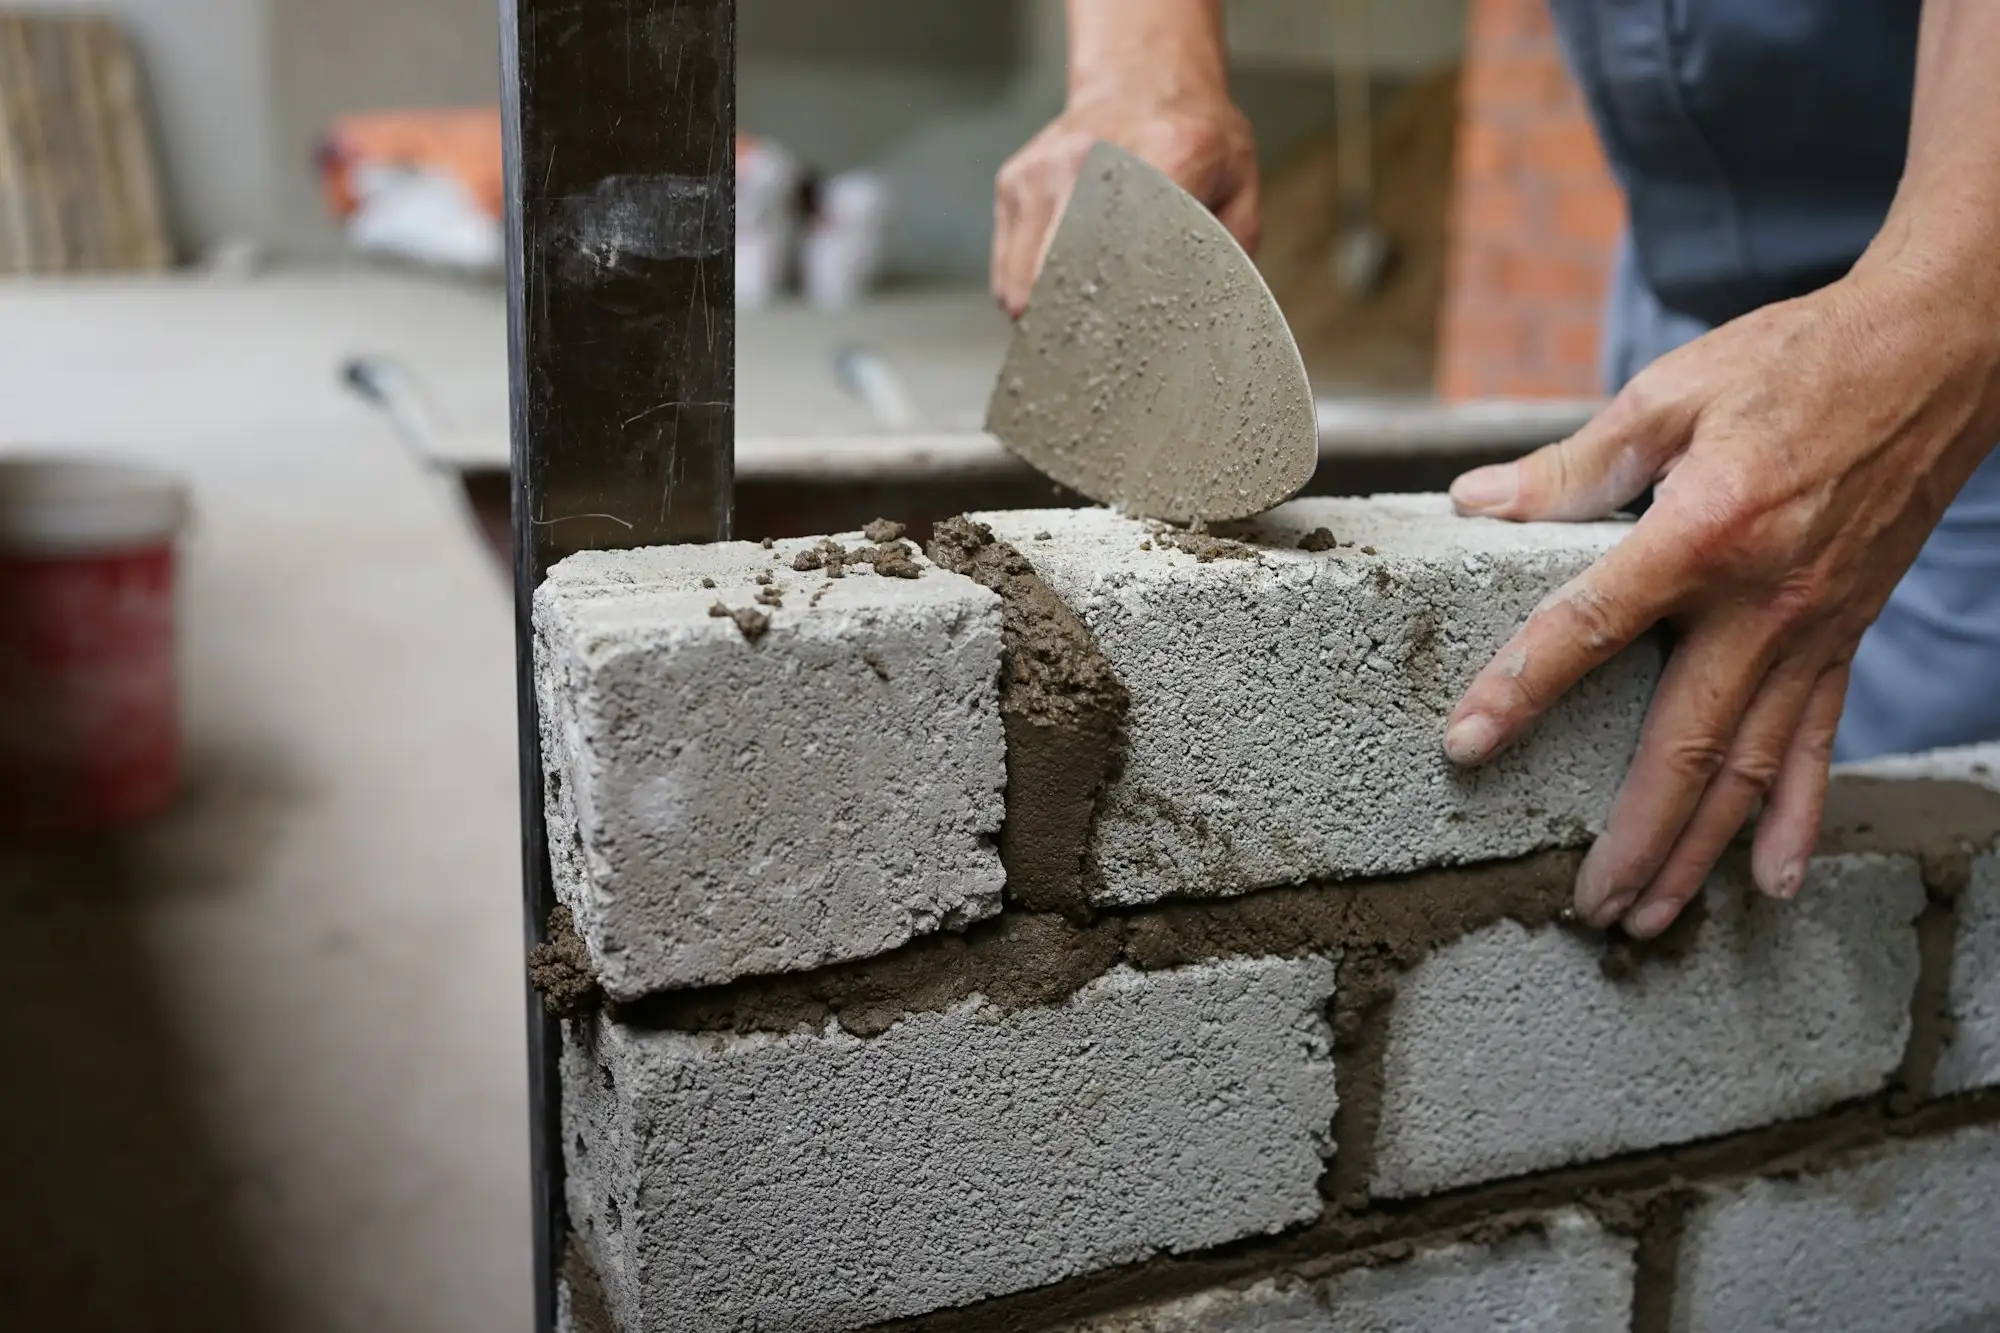
Bricklaying is hard yakka and it’s paid on output. You lay the thousand, you claim the thousand. The problem is that the builder decides when that claim turns into money, and the weather decides how many days you can lay in the first place. Fast bricklayer business loans give you breathing room when both of those go against you.
Why brickies run short of cash
Most bricklayers work as subcontractors to builders, paid per thousand bricks laid or per stage. That model is great when the sun’s out and the slabs are ready. It’s tough when things slip.
- Rain stops everything. A wet fortnight can mean no laying and no claims, but the ute payment, insurance and your labourers’ expectations don’t stop.
- Builders set the pace. Claims are often paid 30 days or more after they’re approved, and approval itself can take a week.
- Gang wages add up fast. A layer or two plus labourers is a serious weekly wage bill.
- Scaffold and equipment. Hiring or buying scaffold, mixers, brick saws and a forklift or telehandler for bigger jobs ties up cash.
For subbies stuck waiting on builders, our subcontractor finance page covers the options in more detail.
What bricklayers use business loans for
- Paying layers and labourers during a payment gap or wet spell
- Buying scaffold, a mixer, brick saws or a small telehandler
- A new tipper ute or trailer
- Putting a second gang on to take more work
- Supply and lay jobs where you buy bricks, blocks, sand and cement up front
- Clearing an ATO debt or overdue supplier account
Using property to secure a bricklayer loan
If you own a home, an investment property or land with equity, you can use it as security. A fast second mortgage is the most common option because it leaves your existing home loan in place. A fast first mortgage suits unencumbered property. If you’re selling a property and need money before it settles, a business bridging loan fills that gap. In Victoria, caveat loans are also available.
There’s no need for financials or tax returns, bad credit is considered, and terms are typically 1 to 12 months.
Unsecured finance for bricklaying businesses
No property to use? An unsecured cash flow loan may suit if you’ve got an ABN, 6+ months of trading and business bank statements showing regular deposits. The amount is based on turnover, and some loans are funded within hours of approval.
Can a bricklayer use a loan to pay the ATO?
Yes. When the builder pays late, the BAS is often the first thing that slips. A fast loan can clear it so you’re not dealing with penalties and letters from the tax office stacking up. Your accountant can help with the tax detail.
Buying a ute, mixer or brick saw
Gear breaks at the worst times. A mixer that seizes or a ute that fails rego can stop a gang for days. A fast business loan lets you replace equipment immediately and keep laying, rather than waiting weeks for a traditional approval.
Stepping up to bigger brickwork contracts
A townhouse job or a small commercial building can mean weeks of steady laying, but it also means more labour and more scaffold before the first claim lands. For businesses with a few crews on the go, working capital for construction companies explains how to fund growth without stretching every account.
Example: a brickie after a wet month
Hypothetical example. A bricklayer in Adelaide runs two gangs. A wet July wipes out nearly two weeks of laying, and two builders are 40 days behind on claims totalling $60,000. He needs to keep his best layers or risk losing them to a competitor. He owns a rental property with equity. A $75,000 second mortgage over three months pays wages and scaffold hire through the gap, and he repays when the builders catch up.
What to have ready
- Photo ID and ABN
- Property details and current loan balance if you’re borrowing against it
- Business bank statements for an unsecured loan
- Your repayment plan, such as claims due, a property sale or a refinance
Key facts for bricklayers
- Borrow: $20,000 to $5 million
- Security: home, investment property, commercial property or land, or unsecured with 6+ months of trading
- Speed: as little as 24 hours for some property loans
- Term: property secured loans typically 1 to 12 months
- Suits: brick and block layers, gang leaders, supply and lay contractors
- Pricing: priced on your circumstances, at the sharpest rate available for your situation
Loans are for business purposes only. When you’re ready, see if you qualify in about 60 seconds and a lending specialist will call you back.